
| Line item | Year 1 | Year 2 | Year 3 | Year 4 | Year 5 |
|---|---|---|---|---|---|
| Revenue | $1,000,000.00 | $1,080,000.00 | $1,166,400.00 | $1,259,712.00 | $1,360,488.96 |
| EBITDA | $280,000.00 | $302,400.00 | $326,592.00 | $352,719.36 | $380,936.91 |
| Net income | $166,875.00 | $182,325.00 | $198,927.00 | $216,773.16 | $235,963.01 |
| Cash from operations | $194,094.18 | $216,902.53 | $236,270.74 | $257,104.40 | $279,520.75 |
| Capital expenditure | $50,000.00 | $54,000.00 | $58,320.00 | $62,985.60 | $68,024.45 |
| Ending cash | $234,094.18 | $366,996.71 | $514,947.45 | $679,066.25 | $860,562.54 |
| Ending debt | $230,000.00 | $210,000.00 | $190,000.00 | $170,000.00 | $150,000.00 |
| Total assets | $708,313.36 | $863,553.42 | $1,035,628.70 | $1,225,801.99 | $1,435,437.15 |
| Liabilities and equity | $708,313.36 | $863,553.42 | $1,035,628.70 | $1,225,801.99 | $1,435,437.15 |
| Balance check | $0.00 | $0.00 | $0.00 | $0.00 | $0.00 |
How do the statements connect?
Ending cash = opening cash + net income + depreciation − change in working capital − capex + debt movement − dividendsRevenue and cost assumptions produce net income. Receivable, inventory and payable days convert operations into working-capital balances. Capital expenditure and depreciation roll net PP&E forward. Debt movement and dividends feed financing cash flow, while retained earnings roll forward from net income less dividends.
Worked base case
The sample starts with $120,000.00 of cash and $250,000.00 of debt. Year 1 revenue is $1,000,000.00, EBITDA is $280,000.00, and cash closes at $234,094.18. Total assets and liabilities plus equity differ by $0.00, so the check passes without a cash or equity plug.
Which assumptions matter most?
Test revenue growth, gross margin and receivable days one at a time. Growth changes all three statements; margin changes operating cash generation; receivable days changes the cash tied up in working capital. The workbook includes visible base, downside and upside scenario inputs.
What does the model check?
- The balance sheet balances within one cent in every period.
- Ending cash equals opening cash plus the cash-flow statement movement.
- Debt and retained earnings reconcile from opening to closing balances.
- Opening balances cannot imply negative share capital.
Limitations and failure states
This educational model uses annual periods, constant operating ratios and a user-entered debt movement. It does not model monthly seasonality, deferred taxes, lease accounting, share repurchases, multiple debt tranches or circular cash sweeps. It is not a filing, fairness opinion, credit decision or investment recommendation.
Actual workbook preview
See exactly what you will receive
These are direct renders of the delivered three-statement model workbook—not a reconstructed mockup. Open any image to inspect the full-size sheet before requesting the file.
Change assumptions and scenarios without editing calculation cells.
Trace values pulled from assumptions and connected schedules.
Dedicated checks identify whether the workbook reconciles and where to investigate.
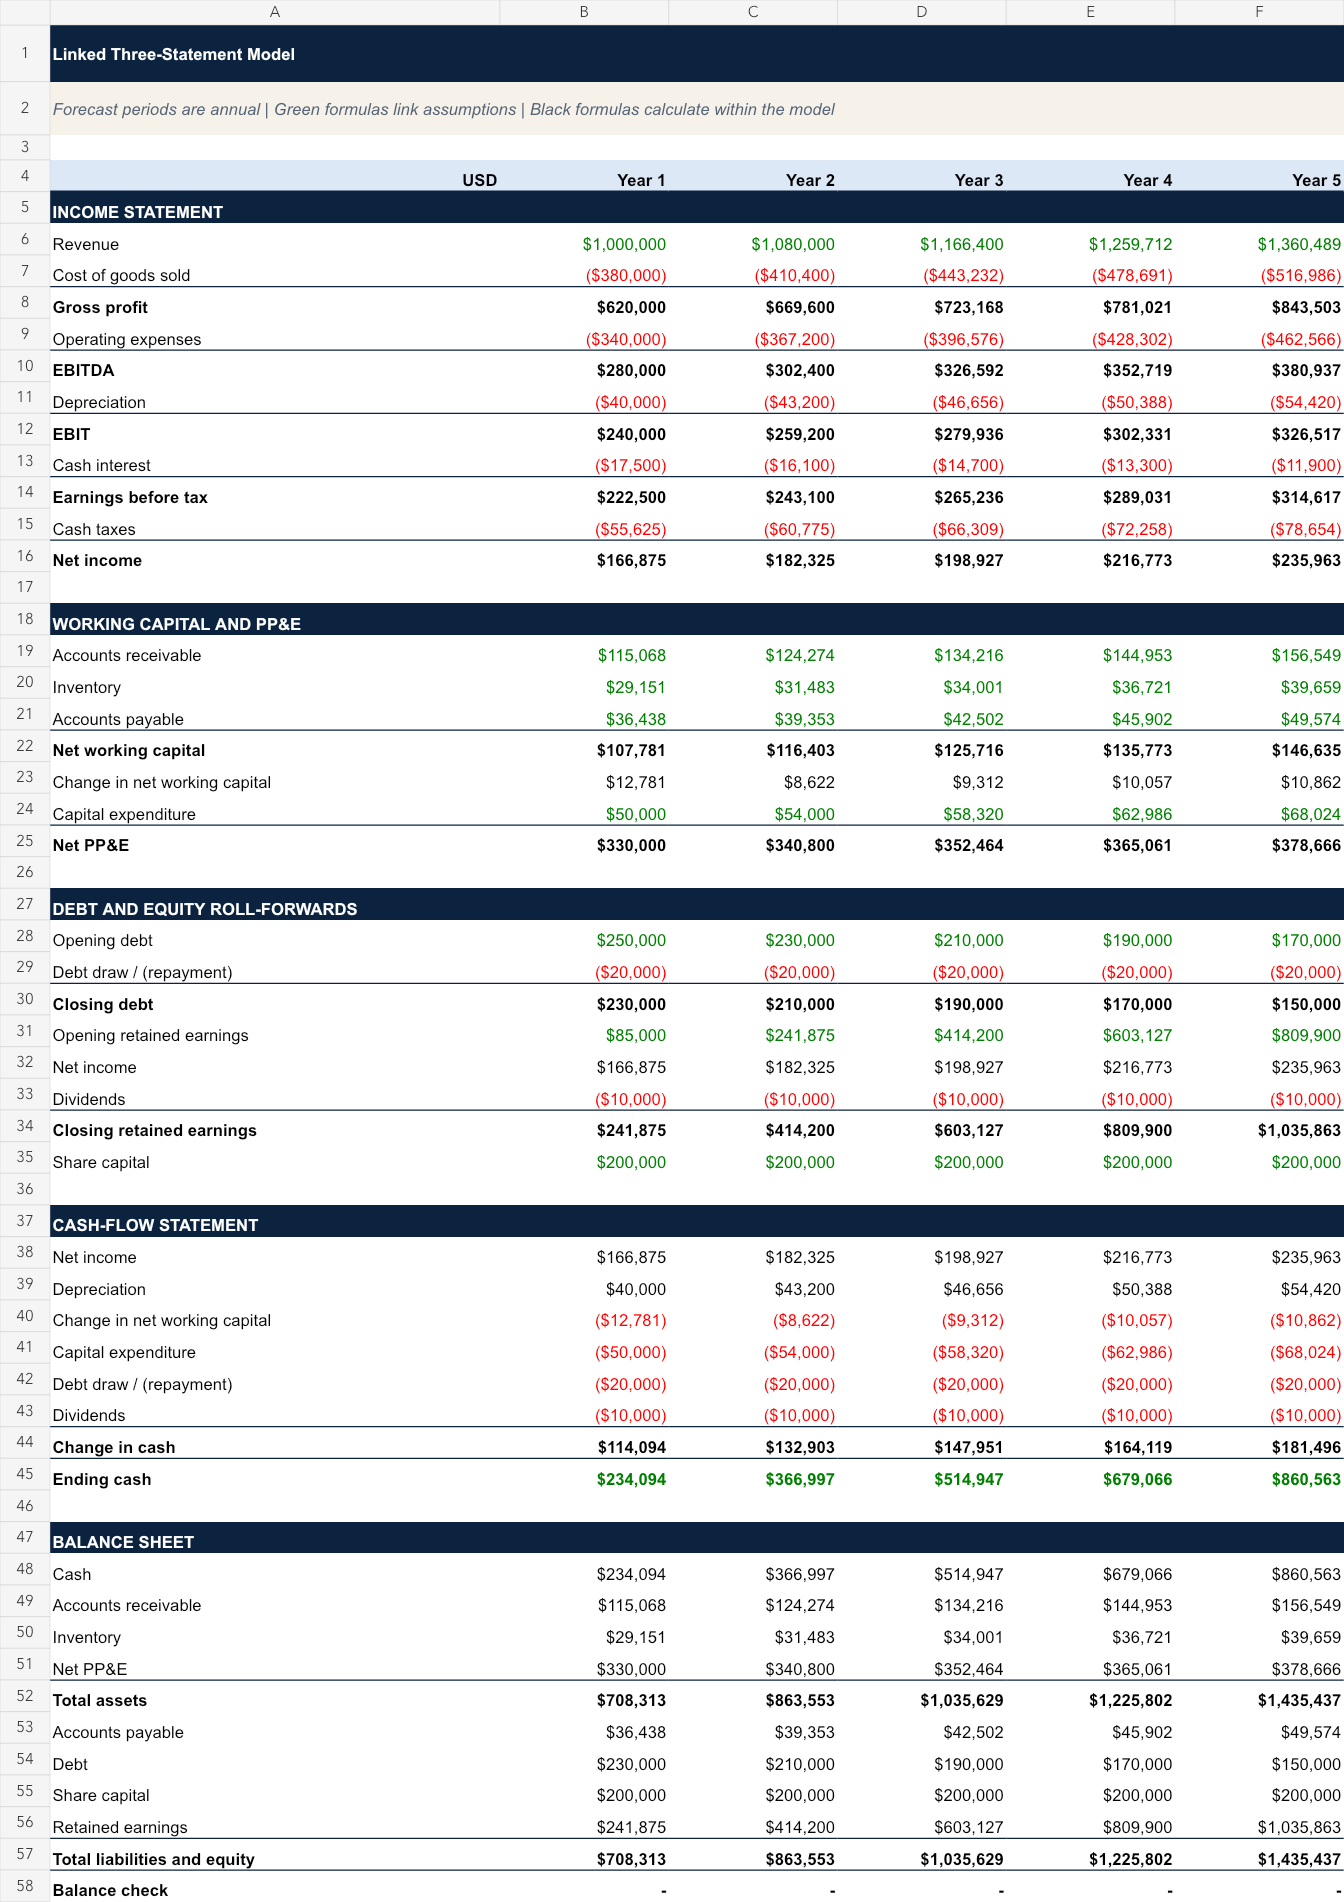
Look for: the five annual columns, statement connections, debt and retained-earnings roll-forwards, and the balance check at the bottom.
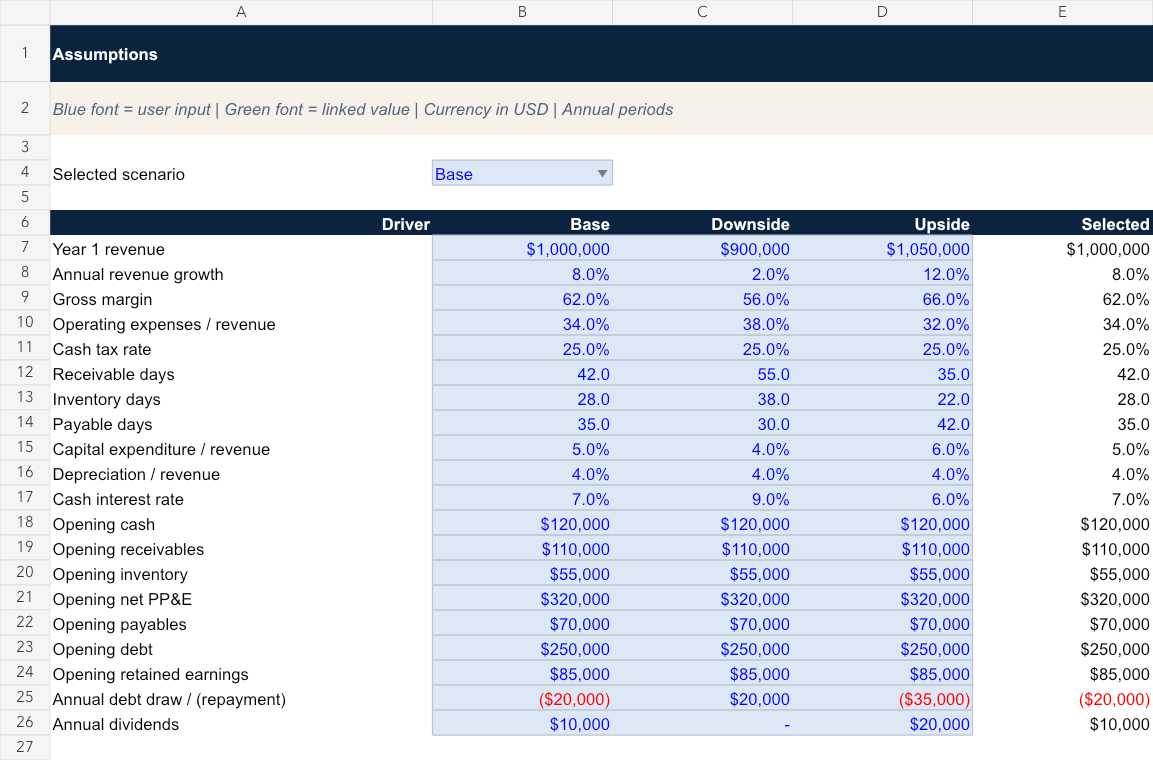
Look for: the scenario selector and blue editable cells for revenue, margins, working capital, capital expenditure, debt and dividends.
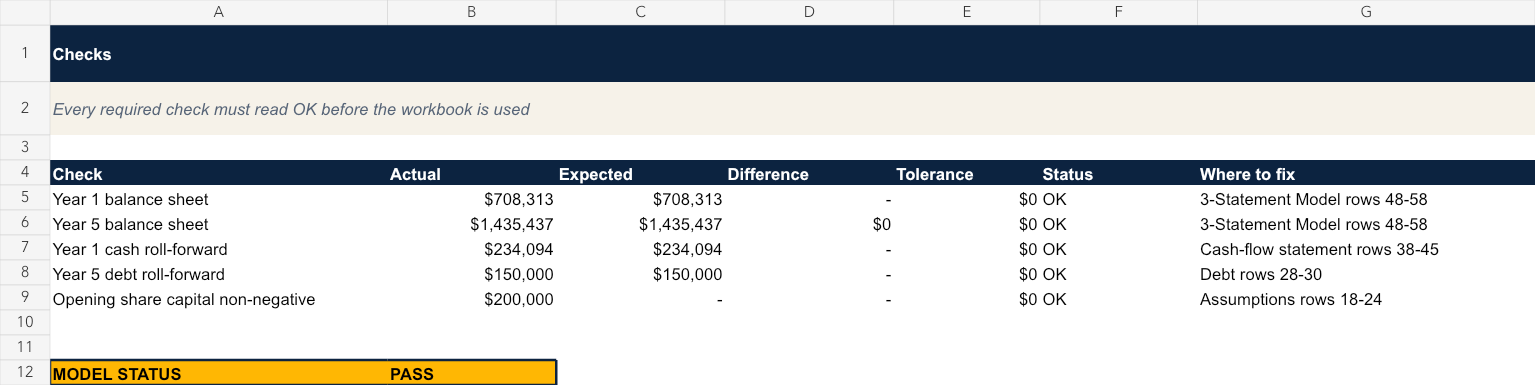
Look for: actual versus expected balances, zero differences and the visible PASS control before the workbook is used.
Included in the file
- Five-year linked income statement, cash-flow statement and balance sheet
- Base, downside and upside operating scenarios
- Working-capital, PP&E, debt and retained-earnings roll-forwards
- Dedicated reconciliation checks with fix locations
- Cover, usage guidance and source notes
Free editable Excel workbook
Get the three-statement model
The workbook is free and contains the exact model shown above: editable assumptions, linked formulas, checks and source notes.
The browser calculator above is free with no sign-up. Email is used only to deliver the workbook; marketing permission is separate and optional.
Sources, version and review status
Statement definitions and relationships are checked against Beginners’ Guide to Financial Statements. Spreadsheet mechanics use the same deterministic fixtures as the browser model. Version 1.0 was last checked on 2026-08-25. Methodology review is complete; no named external expert reviewer is claimed.
Related models and formulas
Frequently asked questions
What is three-statement financial model?
A three-statement model links an income statement, balance sheet and cash-flow statement through shared operating, working-capital, investment and financing assumptions.
How should I use three-statement financial model?
Use the formula only after matching every input to the same period, unit and definition. Then compare the result with a worked example and the decision you are trying to make.
What is the most common mistake with three-statement financial model?
The most common mistake is forcing the balance sheet to balance with an unexplained cash or equity plug instead of using linked roll-forwards.
Can I calculate three-statement financial model in a spreadsheet?
Yes. Reproduce the displayed equation with separate cells for each input, keep percentages as decimals, and test the spreadsheet against the worked example before replacing the sample figures.